Home › Blog › Insurance & Roof Damage
Homeowner Guide
Does Homeowners Insurance Cover Roof Damage in North Carolina?
What's usually covered, what isn't, how wind and hail deductibles work, and what to do after a storm hits your roof.
Request a Free QuoteTakes about a minute · Free estimates · No obligation
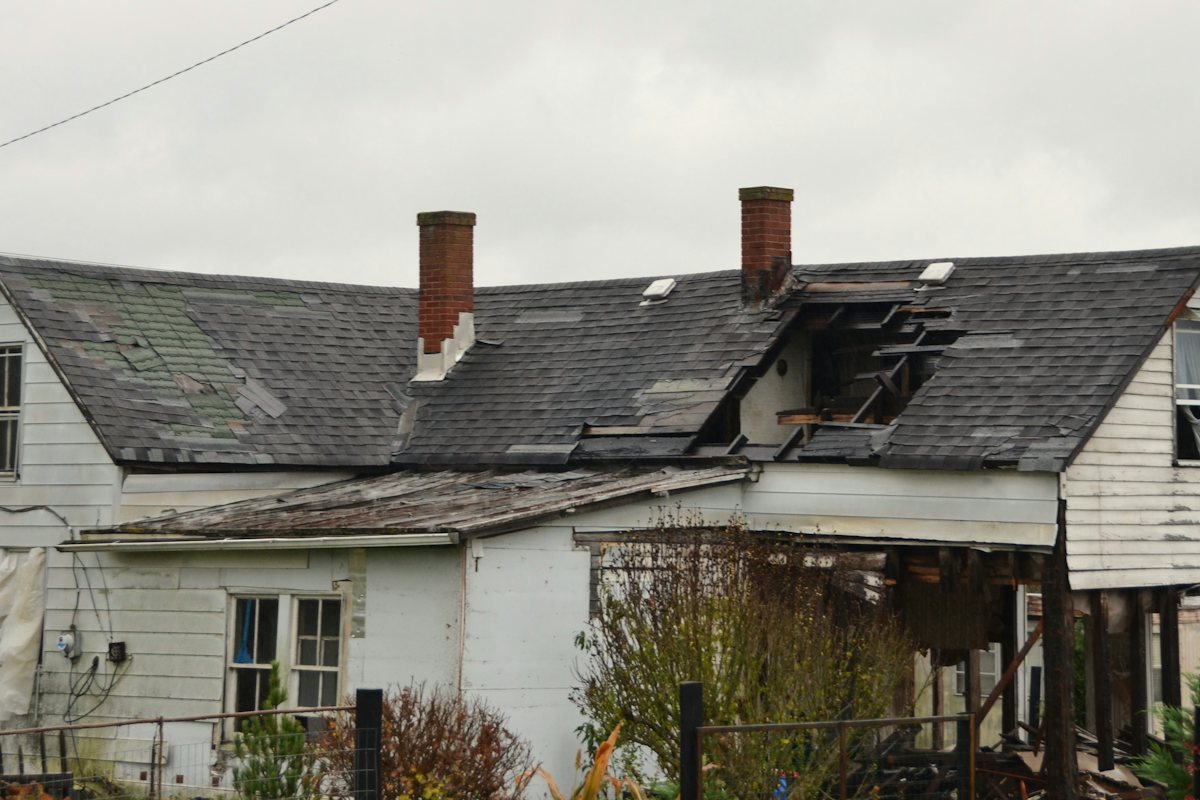
After a big storm rolls through Fuquay-Varina, the same question comes up in every neighborhood: will insurance pay for my roof? The honest answer is that it depends on what caused the damage, what your policy says, and how you handle the first few days. Here's how it generally works in North Carolina.
Note: This is general information, not legal or insurance advice. Your policy and your insurance company make the final call, so read your declarations page and talk to your agent.
Sudden damage vs. wear and tear
Homeowners insurance is built to cover sudden, accidental damage. For roofs, that usually means:
- Shingles torn off by wind
- Hail damage
- A tree or large limb falling on the roof
- Fire
What it generally does not cover is a roof that has simply worn out. Curling shingles, granule loss from age, and slow leaks from neglected flashing are considered maintenance. If a 25-year-old roof starts leaking on a calm day, expect that claim to be denied.
Coverage can also vary by policy. The NC Department of Insurance notes that some companies' underwriting rules can exclude wind or hail damage, so it's worth confirming what yours includes before storm season.
Your deductible may be bigger than you think
Many North Carolina policies have a separate wind and hail deductible that's a percentage of your dwelling coverage instead of a flat dollar amount. The NCDOI's own example: with $200,000 of coverage and a 1% wind and hail deductible, you'd pay the first $2,000 of each wind or hail claim. At 2% on a $300,000 home, it's $6,000.
Some policies also have a named storm deductible that applies to hurricanes and tropical storms. It kicks in when the National Weather Service issues a watch, warning or advisory for any part of the state, so a hurricane that makes landfall at the coast can still trigger it for wind damage here.
Look for both on your declarations page. If your repair estimate is close to your deductible, a claim may not be worth filing.
They may not replace the whole roof
A common surprise: insurers are generally only required to pay for the area that was actually damaged, even if the new shingles won't match the old ones. A full replacement usually happens when the damage is widespread or the roof can't be repaired properly.
How much you get also depends on your loss settlement terms. Replacement cost coverage pays what it costs to repair or replace today. Actual cash value coverage subtracts depreciation, so an older roof pays out less. Some policies settle roof surfaces at actual cash value even when the rest of the house is on replacement cost.
What to do after storm damage
The NC Department of Insurance recommends these steps:
- Stay safe. Don't climb on a wet or damaged roof, and stay away from downed power lines.
- Document everything. Take clear photos and make a list of the damage before any temporary repairs.
- Prevent more damage. A tarp over the damaged area is a reasonable step. Keep every receipt, since reasonable protective costs may be reimbursed.
- Report the claim to your agent or insurance company.
- Hold off on permanent repairs until the insurer has had a chance to inspect.
- Ask before throwing anything away. The adjuster may want to see damaged materials.
Your insurer should acknowledge your claim within 30 days. There's no fixed deadline for settling it, so ask your adjuster what they need to keep things moving.
A good roofer makes the claim easier
A local roofer can inspect the roof, photograph the damage up close, write a detailed estimate, and in many cases meet your adjuster on site so nothing gets missed. That's especially helpful with hail, which can be hard to spot from the ground. Be cautious with out-of-town crews who knock on doors after a storm and ask you to sign right away.
If you think your roof took a hit, start with a free storm damage inspection. And if you're weighing a full replacement, our new roof cost guide covers what to expect.
Request Your Free Quote
Answer a few quick questions and a local roofer will reach out to set up your free estimate.
- 100% free
- No obligation
- Takes about a minute
Your info is only used to contact you about your project. No spam, ever.
Common Questions
Will filing a roof claim raise my rates?
It can affect your rates or renewal depending on your insurer and claim history. Ask your agent before you file if you're unsure.
Does insurance cover a roof leak?
If a covered event like wind or a falling tree caused the leak, usually yes, minus your deductible. If the leak comes from age or lack of maintenance, usually no.
Does insurance pay to remove a tree that fell on my roof?
Many NC policies pay a limited amount for tree removal when the tree damages a covered structure. The tree damage to the roof itself is handled as part of the claim.
Should I call my insurance company or a roofer first?
Getting a roofer's inspection and photos first helps you decide whether the damage is worth a claim, especially if you have a percentage deductible.
Get a Free Estimate
One quick request gets you a free inspection and a written estimate.
Request a Free Quote